
Government bond yields climbed across the United States, Japan, the United Kingdom and Germany on Tuesday as renewed U.S.-Iran hostilities pushed oil prices higher and revived concerns that inflation could remain elevated for longer.
The sell off in government debt reflects a sharp reassessment by investors of the global interest rate outlook. Japan's 10-year government bond yield reached 3% for the first time since 1996, while U.S. Treasury yields also climbed and British and euro zone borrowing costs moved to multi-year highs.
The immediate catalyst was renewed military confrontation between the United States and Iran. Oil prices rose more than 2% on Tuesday after U.S. President Donald Trump threatened further attacks on Iran, raising fears that a prolonged conflict could disrupt energy supplies and keep fuel prices elevated.
Bond yields generally rise when investors sell government debt. In this case, markets are responding to a combination of higher energy prices, inflation concerns, expectations for interest rates and growing government borrowing needs.
Higher oil prices can feed into transportation, manufacturing and household energy costs, making it more difficult for central banks to bring inflation back to target.
That has caused investors to reconsider expectations for monetary easing. Reuters reported that the latest increase in yields has raised the possibility of further interest-rate increases in some major economies if inflation fails to cool.
The U.S. is facing an additional challenge from persistent fiscal pressures. Reuters has previously identified heavy government borrowing, resilient economic growth and inflation risks from Middle East energy disruptions as important factors behind the rise in longer-term Treasury yields.
Japan's move is particularly significant. The country's 10-year government bond yield reaching 3%, its highest level since 1996, marks a major change after decades in which Japanese interest rates and government bond yields remained exceptionally low.
The rise reflects not only global inflation concerns but also questions surrounding Japan's fiscal position and expectations that the Bank of Japan could tighten monetary policy further.
Japan's government debt exceeds 200% of GDP, meaning higher borrowing costs could eventually increase the cost of servicing public debt. At the same time, higher domestic bond yields could make Japanese assets more attractive relative to overseas investments.
That matters globally because Japanese investors are major participants in international bond markets. If domestic yields become more attractive, Japanese institutions could reduce purchases of foreign government debt or repatriate some capital, potentially putting additional upward pressure on overseas yields.
Rising bond yields can create pressure across equity markets because government bonds compete with stocks for investors' capital.
When relatively low-risk government securities offer higher yields, investors may demand greater returns from equities before accepting the additional risk.
Higher yields can be particularly challenging for technology and other growth companies, whose valuations depend heavily on profits expected many years into the future. Higher interest rates reduce the present value of those future earnings.
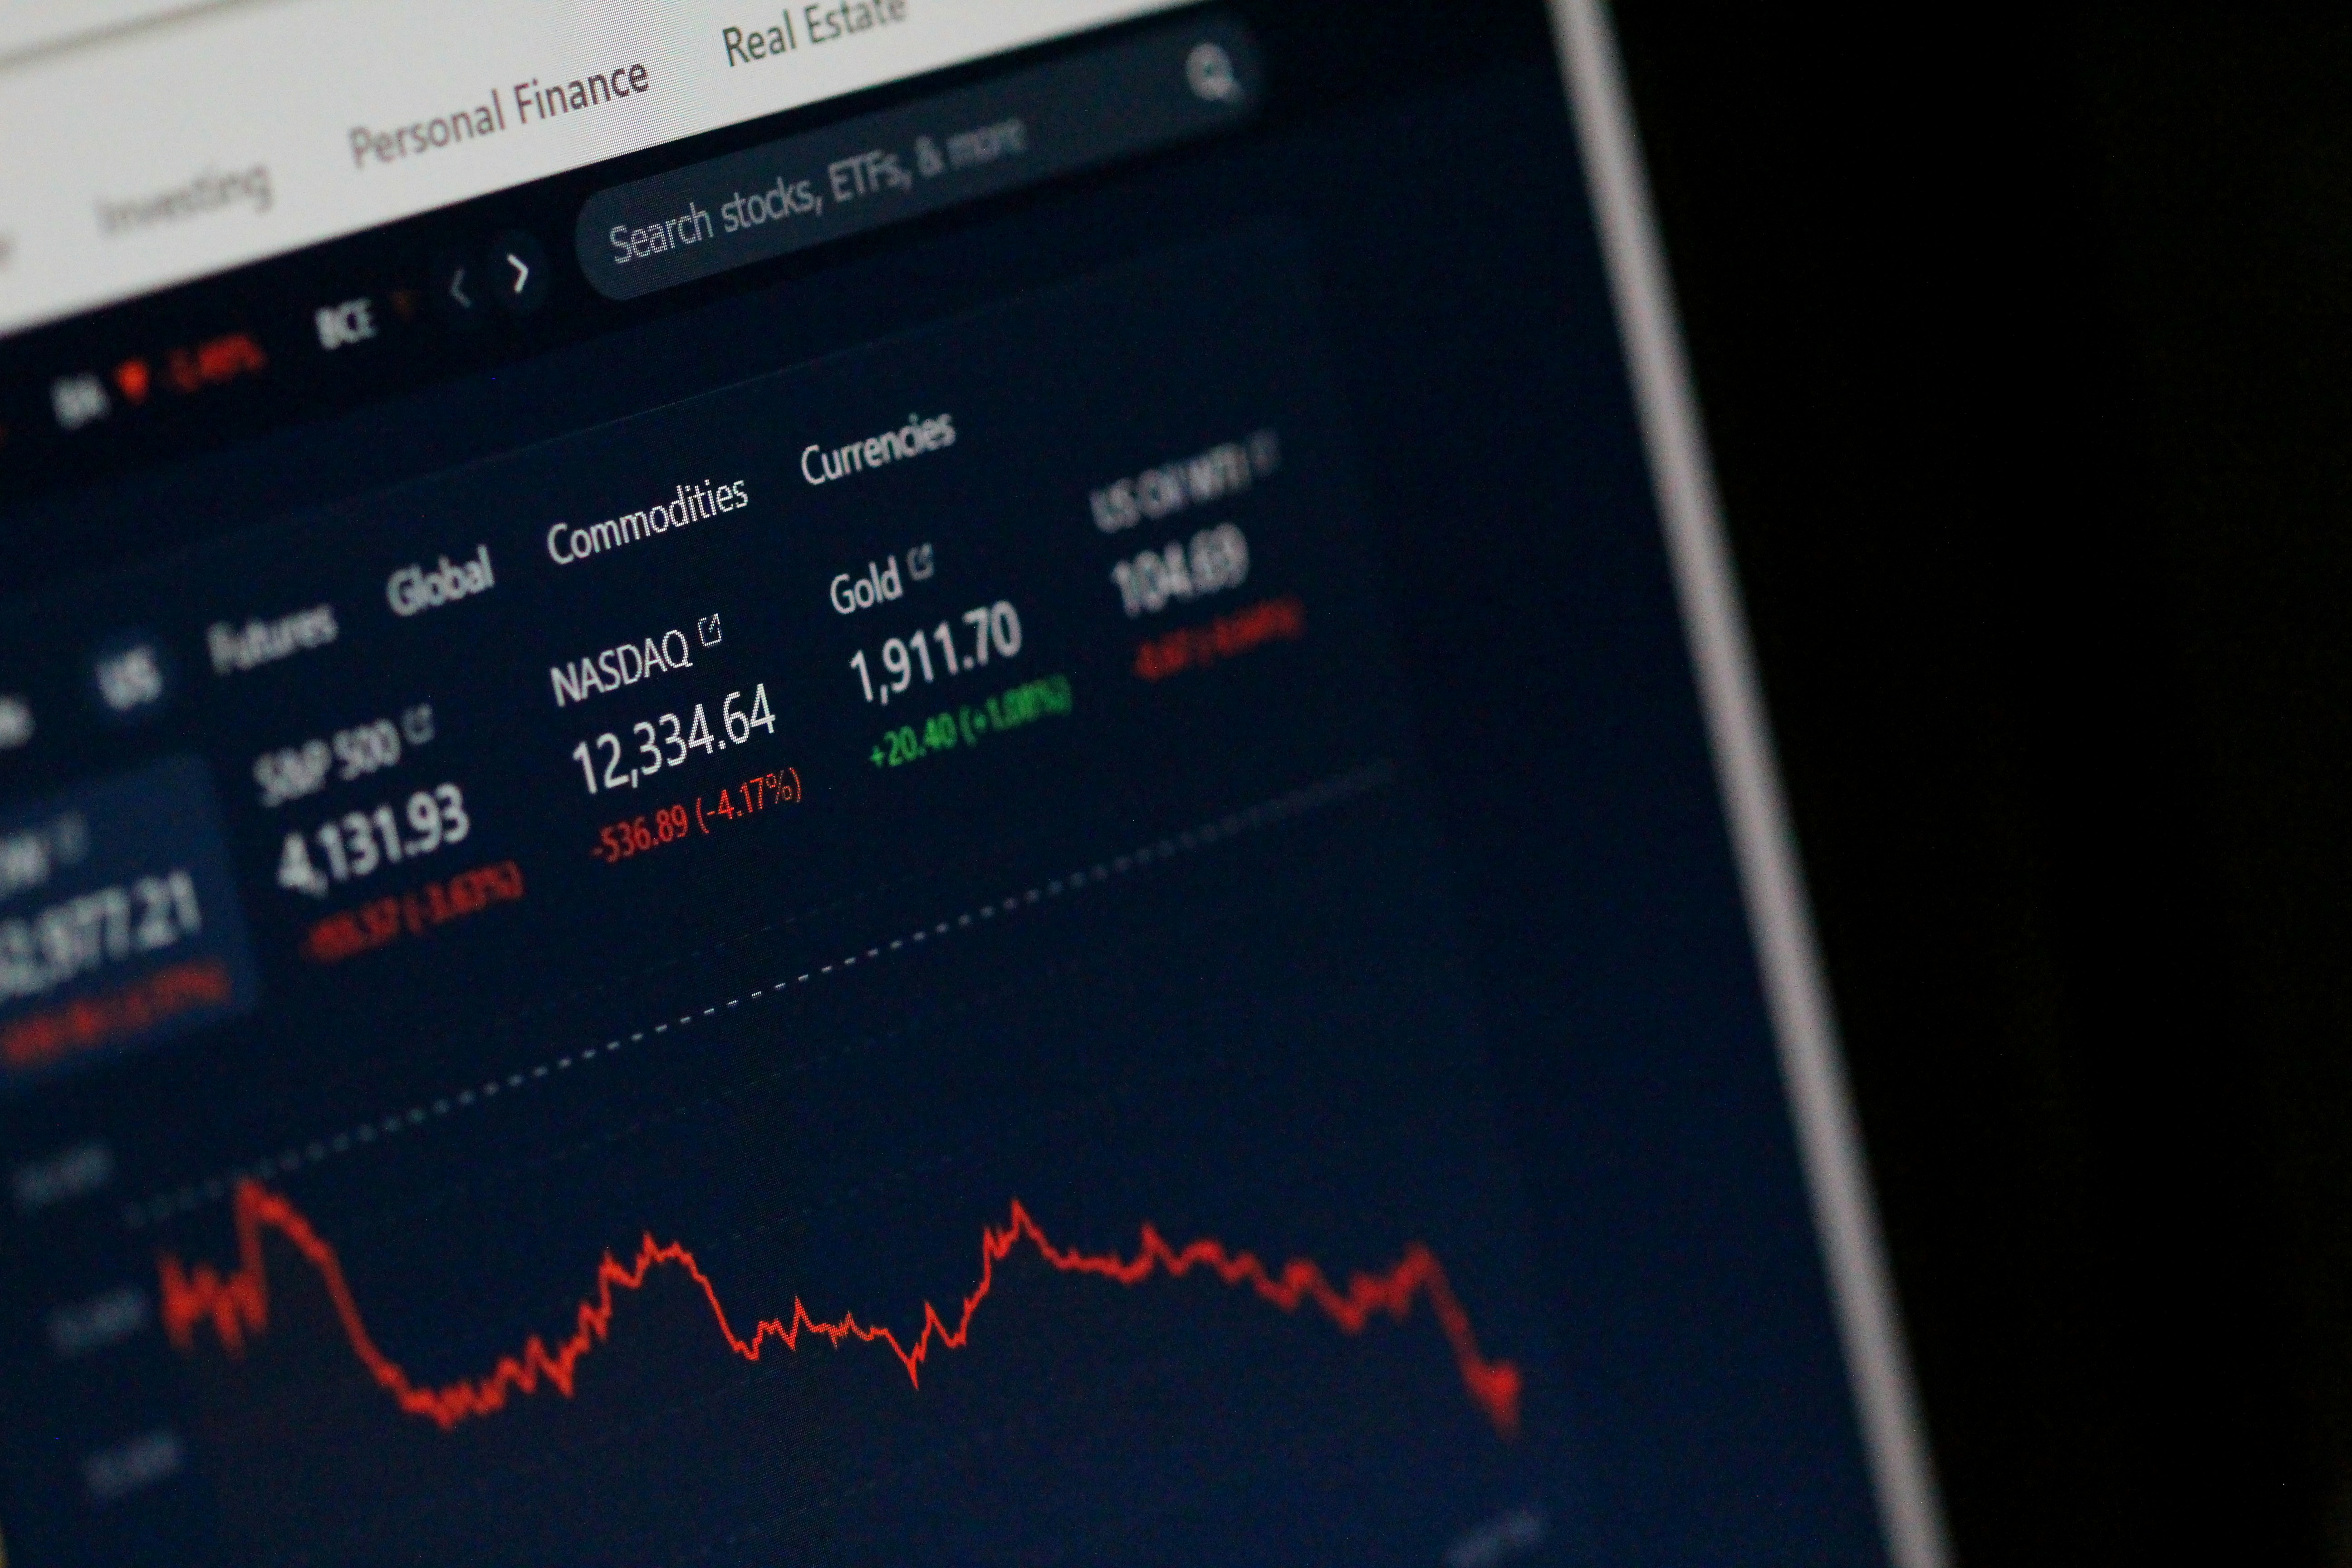
The latest bond sell-off has already been accompanied by weakness in global stocks, with investors weighing the impact of higher oil prices and potentially tighter monetary policy.
The implications extend beyond financial markets. Government bond yields serve as important benchmarks for mortgages, corporate loans and other forms of borrowing. If sovereign yields remain elevated, businesses and households could face higher financing costs.
Governments could also face greater pressure because issuing new debt becomes more expensive. Countries with large fiscal deficits or high debt burdens are particularly exposed.
For emerging markets, higher yields in the United States and other developed economies can make local assets relatively less attractive, potentially encouraging capital to flow toward developed-market bonds and putting pressure on emerging-market currencies.
The biggest challenge is the possibility of stagflationary pressure, a combination of weaker economic growth and higher inflation.
If the Iran conflict pushes oil prices significantly higher for an extended period, central banks could face a difficult choice. Cutting interest rates could support economic growth but risk allowing inflation to remain elevated. Keeping rates high, or raising them, could help contain inflation but put additional pressure on economic activity.
The Bank of Japan is already facing expectations of faster monetary tightening. A Reuters poll published last week showed economists expecting the BOJ to raise its policy rate to 1.25% in September, as inflation pressures and yen weakness increase.
The U.S. Federal Reserve is also under pressure to balance inflation against economic growth. U.S. inflation remained above the Fed's 2% target in July, according to Reuters, complicating the outlook for monetary policy.
For investors, the latest bond-market sell off is more than a temporary reaction to geopolitical tensions. It reflects a broader reassessment of the relationship between inflation, government debt, energy prices and interest rates.
If the conflict eases and oil prices retreat, some of the pressure on bonds could reverse. But if energy prices remain elevated while governments continue borrowing heavily, global investors may have to adjust to a prolonged period of higher yields and tighter financial conditions.
That would have consequences across the investment landscape, from government and corporate bonds to stocks, currencies, real estate and emerging markets.
Comments (0)
You must be logged in to post comments.
No comments yet. Be the first to start the conversation!